How Many Times Can You Get an Advance on Universal Credit in 2026?
A person can receive more than one form of Universal Credit advance during the time they claim Universal Credit, but they cannot simply request unlimited advances whenever they need extra money.
Each type of advance has its own purpose, maximum amount, eligibility conditions and repayment rules.
For example, a First Payment Advance is connected to the beginning of a Universal Credit claim, while a Budgeting Advance may be available again after an earlier Budgeting Advance has been fully repaid.
Recoverable Hardship Payments work differently because a new application may be required for each qualifying reduced or missed Universal Credit payment.
This means the answer to how many times can you get an advance on Universal Credit depends mainly on the type of financial help being requested.
How Many Times Can You Get an Advance on Universal Credit?
There is no single annual or lifetime number of Universal Credit advances that applies to every claimant.
Instead, the Department for Work and Pensions applies different rules to different types of advances.
A claimant may potentially receive several advances over the course of a long Universal Credit claim if each application relates to an eligible situation.
However, this does not mean several advances of the same type can always be outstanding at once.
For example, only one Budgeting Advance can normally be outstanding at a time. Once that advance has been repaid, another application may be possible if the claimant still meets the eligibility conditions.
Change of Circumstances Advances depend on an eligible change that increases Universal Credit, while Recoverable Hardship Payments can require repeat applications when qualifying payments continue to be reduced or missed.
Is There a Yearly or Lifetime Limit on Universal Credit Advances?
There is no general rule saying a claimant can only receive Universal Credit advances a certain number of times per year or throughout their lifetime.
The restriction is normally connected to the type of advance, existing debt and current circumstances rather than a fixed yearly number.
For example:
- First Payment Advance: Linked to the start of a Universal Credit claim
- Budgeting Advance: Another may be considered after the previous Budgeting Advance has been repaid
- Change Of Circumstances Advance: May be available following a qualifying change that increases entitlement
- Recoverable Hardship Payment: A fresh application may be required for each qualifying reduced or missed payment
Receiving financial help previously therefore does not automatically prevent a claimant from receiving another type of Universal Credit advance later.
What Types of Universal Credit Advances Are Available?
Understanding the different types is important because the rules about repeat applications are not the same for every advance.
First Payment Advance
A First Payment Advance is intended for people who cannot manage financially while waiting for their first regular Universal Credit payment.
The maximum available is normally the amount of the claimant’s estimated first Universal Credit payment.
The advance must be repaid and repayments are normally taken from future Universal Credit payments over a period of up to 24 months.
Budgeting Advance
A Budgeting Advance can help with certain unexpected or one-off expenses.
This could include:
- Furniture Or Household Equipment
- Clothing And Footwear
- Essential Home Repairs
- Rent Deposits Or Moving Costs
- Funeral Expenses
- Certain Costs Connected With Starting Or Staying In Work
The minimum Budgeting Advance is £100.
In 2026, the maximum amounts are:
| Circumstances | Maximum Budgeting Advance |
| Single Claimant | £348 |
| Couple | £464 |
| Household With Children | £812 |
A claimant can only have one Budgeting Advance outstanding at a time.
Change Of Circumstances Advance
A Change of Circumstances Advance may be available when a change means the claimant will become entitled to more Universal Credit but has not received the increased amount yet.
Examples can include:
- Having A Child
- Rent Increasing
- Losing A Job
- Earnings Falling
The change must first be reported to Universal Credit.
The claimant must also apply before receiving the increased Universal Credit payment resulting from that change.
Recoverable Hardship Payment
A Recoverable Hardship Payment is different from the normal advance types.
It may be available when Universal Credit has been reduced or stopped because of a sanction or qualifying fraud penalty and the claimant cannot afford essential living costs.
It can help with necessities such as food, heating, hygiene and certain housing costs.
The payment must later be repaid.
Can You Get More Than One Universal Credit Advance?
Yes, it is possible to receive more than one Universal Credit advance over time.
However, receiving one advance does not automatically make someone eligible for another.
For example, a claimant might receive a First Payment Advance when initially moving onto Universal Credit.
Months later, after meeting the qualifying conditions, the same person could need a Budgeting Advance because an essential household appliance has unexpectedly broken.
These are different types of support designed for different circumstances.
The DWP will consider the rules applying to the particular advance requested rather than simply counting how many advances the claimant has received previously.
Can You Ask for More Advance Money Before Your First Universal Credit Payment?
The amount available through a First Payment Advance is limited by the claimant’s estimated first Universal Credit payment.
A claimant cannot use advances to receive more than the maximum amount available under the First Payment Advance rules.
Anyone who has already received help but believes they did not request the full amount available should contact Universal Credit to establish whether any further amount remains available before their first payment.
The claimant’s circumstances, amount already advanced and estimated entitlement will determine what further support may be available.
When Can You Get Another Budgeting Advance?
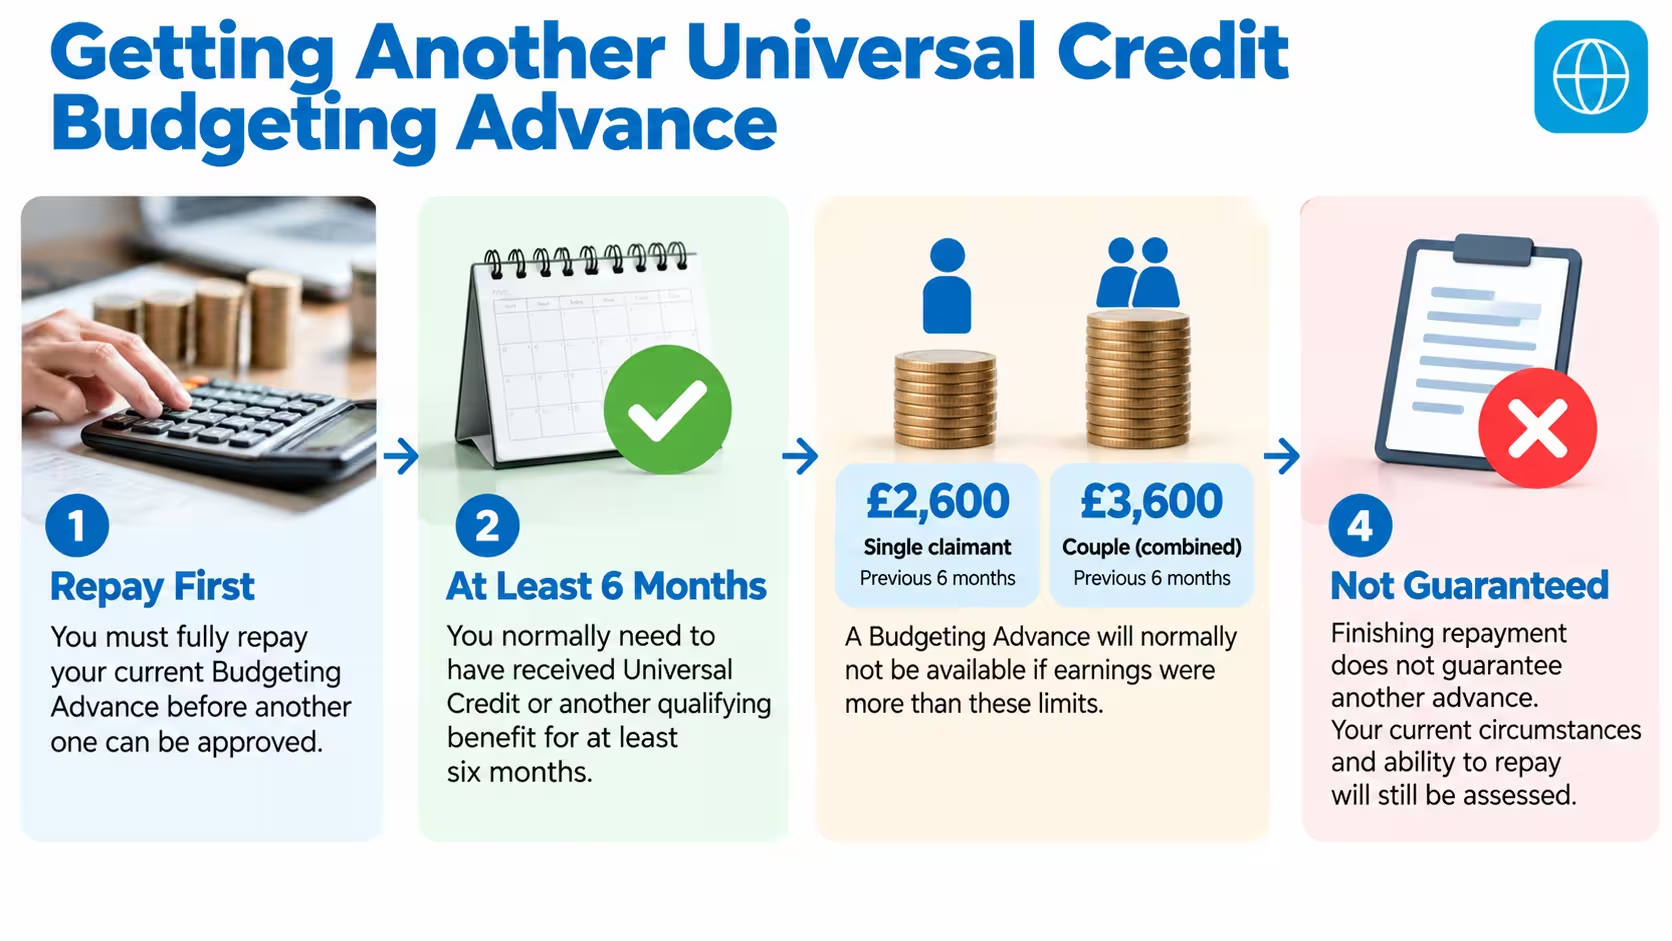
A claimant will normally need to fully repay an existing Budgeting Advance before another one can be approved.
They must also continue to satisfy the qualifying rules.
Generally, a claimant must have received Universal Credit or another qualifying benefit for at least six months. An exception can apply where the money is required to help someone start a new job or remain in work.
There are also earnings limits.
A Budgeting Advance will normally not be available if earnings during the previous six months were more than:
- £2,600 For A Single Claimant
- £3,600 Combined For A Couple
Finishing repayment of an earlier Budgeting Advance does not guarantee another one. The claimant’s latest circumstances and ability to repay will still be considered.
What Happens If You Reach the Limit for a Universal Credit Advance?
Reaching a maximum advance amount does not mean a claimant has permanently used up their Universal Credit support.
Instead, it normally means no more money can be provided through that particular advance at that point.
For example, a First Payment Advance cannot exceed the maximum based on the estimated first Universal Credit payment.
For a Budgeting Advance, the maximum in 2026 is £348 for a single claimant, £464 for a couple and £812 for a household with children.
A person cannot simply request another Budgeting Advance to get around that limit while the existing Budgeting Advance remains unpaid.
If the maximum has been reached, the claimant may need to:
- Wait Until An Existing Budgeting Advance Has Been Repaid
- Check Whether Another Type Of Universal Credit Support Applies
- Speak To Their Work Coach About Employment-Related Support
- Check Whether Local Financial Assistance Is Available
- Discuss Repayment Difficulties If Existing Deductions Are Causing Hardship
The correct option depends on why the additional money is needed.
Can You Apply Again If Your Universal Credit Advance Is Refused?
A refusal does not necessarily prevent a claimant from making another request in the future.
The DWP assesses advance requests according to the claimant’s circumstances and the rules applying to that particular type of advance.
A further request would therefore need to be considered on its own facts.
Reasons an advance might not be approved can include having sufficient accessible money, failing to meet eligibility conditions, already having an outstanding Budgeting Advance or applying for money that the particular advance is not designed to cover.
A claimant should therefore understand the reason for the original refusal before making another request.
How Many Times Can You Get a Recoverable Hardship Payment?
Recoverable Hardship Payments do not follow a simple one-payment limit.
If a claimant continues to receive lower or missed Universal Credit payments because of an eligible sanction or fraud penalty, they may need to make another hardship application each time.
Eligibility must also be demonstrated again.
A claimant may need to show that they:
- Cannot Meet Essential Living Costs
- Have Reduced Non-Essential Spending
- Have Looked For Other Available Support
- Still Meet The Relevant Hardship Conditions
If approved, a Recoverable Hardship Payment is normally paid quickly and must later be repaid through Universal Credit.
What Can Stop You From Getting Another Universal Credit Advance?
There are several reasons why another advance may not be available.
These can include:
- An Existing Budgeting Advance Has Not Been Fully Repaid
- Recent Earnings Are Above The Budgeting Advance Limits
- The Requested Expense Is Not Covered By That Type Of Advance
- The Claimant Has Enough Accessible Money To Meet Their Needs
- A Change Of Circumstances Advance Is Requested After The Higher Payment Has Already Been Received
- The Claimant Does Not Meet The Required Benefit History
- The Requested Amount Exceeds The Maximum Available
Eligibility should therefore be checked against the specific type of advance rather than assuming a previous approval means another request will also succeed.
How Do Universal Credit Advance Repayments Work in 2026?
Universal Credit advances are repayable financial support rather than grants.
Repayments are normally deducted automatically from future Universal Credit payments.
Typical repayment arrangements include:
| Type Of Support | Typical Repayment Period |
| First Payment Advance | Up To 24 Months |
| Budgeting Advance | Usually Up To 24 Months |
| Change Of Circumstances Advance | Usually Around 6 Months |
| Recoverable Hardship Payment | Repaid After The Relevant Sanction Or Penalty Ends |
If a claimant stops receiving Universal Credit before the debt has been cleared, the outstanding amount does not disappear.
Repayment may continue through another benefit or the DWP may arrange another method of repayment.
Can Universal Credit Advance Repayments Be Paused?
Temporary repayment delays may be available when a claimant is experiencing financial difficulty.
The available period depends on the advance.
A First Payment Advance repayment may potentially be delayed for up to three months.
Budgeting Advance repayments may potentially be delayed for up to six months.
Claimants struggling with deductions should contact Universal Credit rather than simply allowing repayment problems to continue.
A repayment delay does not cancel the debt. It temporarily postpones deductions and the outstanding amount will still need to be repaid.
How Much Can DWP Deduct From Universal Credit for Advance Repayments?
Universal Credit deductions are generally subject to an overall limit based on a percentage of the standard allowance.
Under the rules applying in 2026, total deductions are normally capped at 15% of the Universal Credit standard allowance, although certain last-resort deductions can take the total above that level.
These exceptional deductions can include certain housing arrears, energy arrears or child maintenance obligations.
Advance repayments can therefore affect how much Universal Credit reaches the claimant each month, particularly when other debts are also being recovered.
DWP statistics for May 2026 showed that around 21% of Universal Credit households had deductions at the 15% cap, while another 2% had deductions above the cap for permitted last-resort reasons.
What If You Already Have Other Universal Credit Deductions?
An advance repayment may not be the only deduction being made from Universal Credit.
Other deductions can relate to:
- Benefit Overpayments
- Government Debts
- Rent Arrears
- Energy Arrears
- Child Maintenance
- Previous Universal Credit Advances
Having other deductions does not automatically mean a claimant can never receive another advance.
However, affordability and existing debt can be relevant when the DWP decides whether another advance is appropriate.
Claimants should check their Universal Credit payment statement to understand exactly what is being deducted each month.
In May 2026, around 3.3 million Universal Credit households had at least one deduction from their entitlement. The average total monthly deduction among affected households was £53.
How Many People Rely on Universal Credit and Advance Payments in 2026?
Universal Credit now supports millions of people across Great Britain.
Official DWP statistics show that there were approximately 8.4 million people on Universal Credit in May 2026, compared with 7.7 million in May 2025.
There were around 7.2 million Universal Credit households, with approximately 6.7 million receiving a Universal Credit payment during May 2026.
Advance repayment figures also show how widely this form of support has been used.
In May 2026, around 32% of Universal Credit households were repaying advance debt. Advances were the most common of the three main deduction categories measured by the DWP.
The average monthly deduction specifically for advance repayments was around £35.
These figures show that Universal Credit advances are not a rarely used form of support. They form an important part of the system for many households, particularly where money is needed before the first payment or an unexpected essential expense occurs.
At the same time, an advance reduces future Universal Credit payments while it is being repaid. Claimants should therefore consider both the immediate benefit and the effect of later deductions.
Could You Get Help Without Taking Another Universal Credit Advance?
Another Universal Credit advance is not always the only option.
People who need money specifically to start work or remain in employment should speak to their work coach because some employment-related costs may be supported separately.
Depending on circumstances and location, other help may also include local authority support, assistance with housing costs, energy support or charitable help.
This can be particularly important where someone already has deductions from Universal Credit and another repayable advance could place additional pressure on their monthly budget.
Before borrowing again, a claimant should consider:
- Whether The Cost Is Essential
- Whether A Non-Repayable Form Of Help Is Available
- How Much Is Already Being Deducted From Universal Credit
- Whether Another Advance Is Permitted Under The Relevant Rules
- How Future Monthly Payments Would Be Affected
An advance can provide important short-term support, but it should be considered alongside the effect repayments may have on future household finances.
Conclusion
There is no universal yearly or lifetime answer to how many times can you get an advance on Universal Credit.
The number depends on the type of advance and the claimant’s circumstances. A Budgeting Advance may be available again once an existing Budgeting Advance has been repaid and eligibility conditions are still met.
Change of Circumstances Advances depend on eligible changes, while Recoverable Hardship Payments can require a new application for each qualifying reduced or missed payment.
Reaching the maximum amount for one advance does not necessarily prevent someone from receiving other Universal Credit support in the future.
However, advance payments must generally be repaid, meaning future Universal Credit payments will be lower while deductions are being made.
Understanding the type of support needed, existing repayments and current eligibility is therefore essential before requesting another advance.
Frequently Asked Questions
Can You Get a Universal Credit Advance Twice?
Yes. A claimant may receive different Universal Credit advances at different times, depending on eligibility and the reason financial help is required.
Can You Have Two Universal Credit Advances at the Same Time?
It depends on the type of advance. A claimant cannot normally have two Budgeting Advances outstanding because the previous Budgeting Advance must first be repaid.
How Soon Can You Apply for Another Budgeting Advance?
Another Budgeting Advance may normally be requested once the existing Budgeting Advance has been fully repaid, provided all other eligibility conditions are still satisfied.
Can You Get Another Advance Before Paying Off the Previous One?
Another Budgeting Advance is normally unavailable while an existing one remains unpaid. Different advance types have separate rules, so circumstances need to be considered individually.
What Happens If You Cannot Get Another Universal Credit Advance?
A claimant can check whether another form of Universal Credit support, work-related assistance or local financial help is available instead of another repayable advance.
Does Being Refused an Advance Stop You Applying Again?
Not necessarily. A refusal does not create a permanent ban, although any later request must still satisfy the relevant eligibility requirements.
How Long Do Universal Credit Advance Repayments Last?
First Payment Advances and Budgeting Advances are generally repayable over up to 24 months, although repayment arrangements differ depending on the type of financial support.
John covers a wide range of business topics including technology, productivity, startups, digital transformation, and business development for modern companies.
UK Budget Savings Tax Changes 2026: New Rates, ISA Rules and How Much More Savers Could Pay?
The UK Budget savings tax changes announced on 28 October 2026 have introduced significant financial implications for millions of savers, pensioners and small business owners. From 6 April…
DWP Energy Bill Letters Dispatched: Six Million Households Could Get £150 Discount
Millions of UK households are being urged to watch their post as the Department for Work and Pensions (DWP) prepares to distribute letters concerning a £150 reduction in…
Insights for the Modern
UK Small Business.
Join 15,000+ owners receiving tactical analysis on finance, marketing, and technology. No clutter.
Zero spam. Unsubscribe in one click.