Rachel Reeves Pension Tax Raid: £2,000 Cap, Inheritance Tax and What Changes Under Healey
The Rachel Reeves pension tax raid is no longer simply a proposed change to UK retirement savings. The £2,000 National Insurance exemption limit for salary sacrifice pension contributions became law in April 2026 and will take effect on 6 April 2029.
Research suggests the changes could cost some higher-income households nearly £900 annually, while businesses face additional National Insurance liabilities and pension administration costs.
However, Rachel Reeves is no longer Chancellor. John Healey, appointed under Prime Minister Andy Burnham in July 2026, will deliver his first Budget on 28 October.
For employees, company directors and small-business owners, understanding which measures are already law, which remain unchanged and what could happen next is essential.
What Is Rachel Reeves’s Pension Tax Raid?
The term “pension tax raid” refers to several pension-related tax measures and concerns that developed during Rachel Reeves’s time as Chancellor.
The most significant confirmed changes include:
- National Insurance charges on salary sacrifice pension contributions exceeding £2,000 annually from April 2029.
- Most unused pension funds and certain death benefits entering inheritance tax calculations from April 2027.
- Continued income tax threshold freezes that can increase taxation as earnings and pension incomes rise.
Separately, speculation about reducing tax-free pension lump sums has created uncertainty, although no such reduction has been announced.
The distinction matters because these changes affect different people.
Employees using salary sacrifice could face higher National Insurance deductions, while business owners may encounter increased employment costs. Families inheriting pension savings could face additional inheritance tax exposure.
Is the £2,000 Salary Sacrifice Pension Cap Already Law?
Yes. The National Insurance Contributions (Employer Pensions Contributions) Act 2026 received Royal Assent on 29 April 2026.
The legislation establishes the framework for restricting National Insurance exemptions on salary sacrifice pension contributions from the 2029/30 tax year.
Under the new arrangements, the first £2,000 sacrificed annually into a pension remains exempt from employee and employer National Insurance.
Amounts exceeding this threshold become subject to both contributions.
Importantly, the reform does not abolish salary sacrifice or remove the existing income tax relief on qualifying pension contributions.
| Pension contribution arrangement | Treatment from April 2029 |
| First £2,000 through salary sacrifice | NI exemption retained |
| Salary sacrifice exceeding £2,000 | Employee and employer NI charged on excess |
| Ordinary employer pension contributions | NI exemption retained |
| Employee contributions outside salary sacrifice | Existing income tax relief rules continue |
| Self-employed pension contributions | No direct change from salary sacrifice cap |
HMRC’s official salary sacrifice impact assessment confirms that the measure changes National Insurance treatment rather than the underlying income tax relief.
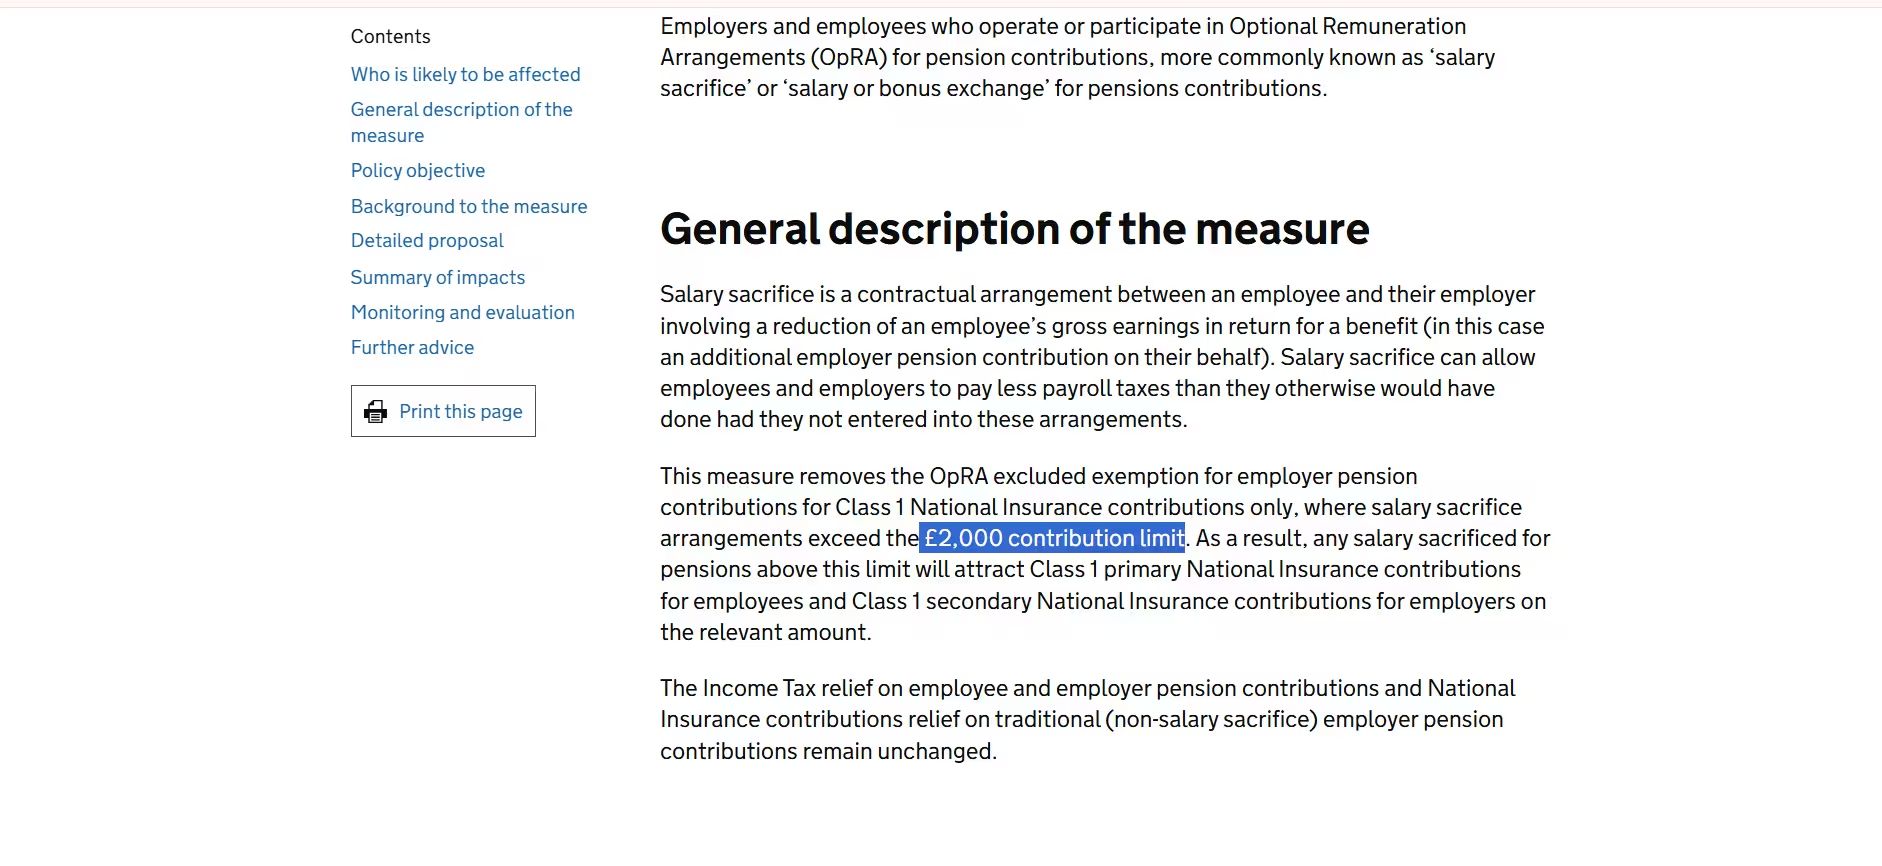
Official HMRC explanation confirming the £2,000 salary sacrifice contribution limit and 6 April 2029 implementation date.
How Many UK Workers Will Be Affected?
Government estimates show that approximately 7.7 million employees currently use pension salary sacrifice arrangements.
Of these, around 3.3 million sacrifice more than £2,000 annually.
That represents approximately 44% of existing salary sacrifice users, while the remaining 56% are below the threshold.
The government has also stated in a parliamentary answer that 39% of employers offer salary sacrifice.
However, indirect effects could be wider if businesses change employment packages or discontinue arrangements.
The Office for Budget Responsibility anticipates that employers will pass approximately 76% of their additional National Insurance costs to employees through reduced salaries, bonuses or ordinary employer pension contributions.
This means employees contributing below the £2,000 threshold might also experience changes if their employer restructures its entire scheme.
How Much Could Employees and Small Businesses Pay?
The financial impact becomes clearer through a worked example.
Consider a small technology company employing someone who sacrifices £5,000 of their annual salary into a workplace pension.
Under the 2029 rules:
| Calculation | Amount |
| Annual salary sacrificed | £5,000 |
| NI-exempt allowance | £2,000 |
| Amount subject to NI | £3,000 |
| Employer NI at 15% | £450 |
| Employee NI at 8% | £240 |
| Employee NI at 2% | £60 |
These are illustrative calculations assuming the stated NI rates continue to apply and the full excess falls within the relevant employee contribution band.
An employee paying the 8% rate could therefore lose approximately £240 of annual take-home pay, while their employer faces another £450 in National Insurance.
For someone paying the 2% employee rate, the additional employee liability would be approximately £60.
A company with ten employees in equivalent circumstances could face £4,500 in additional annual employer NI costs before considering possible changes to its remuneration arrangements.
The calculation illustrates why smaller firms should begin forecasting rather than waiting until 2029.
Could Some Households Lose Nearly £900 Annually?
The Institute for Fiscal Studies published detailed research on the distributional consequences of the reform in May 2026.
Its findings are more specific than suggestions that one million households will automatically lose £900.
The IFS analysis estimated:
| Household impact | IFS finding |
| All households in highest income decile | More than £300 average annual loss |
| Affected households in highest income decile | £888 average annual loss |
| Affected households across income distribution | £540 average annual loss |
| Highest-decile households experiencing no change | Approximately 65% |
These estimates assume unchanged pension contributions and that extra employer NI costs are fully passed through to affected employees’ wages.
They are modelling outcomes, not guaranteed losses.
The £540 figure describes affected households under those assumptions, not the average individual worker.
The IFS found that the direct financial burden would predominantly fall on higher-income households.
Nevertheless, the effect could extend beyond them depending on how employers respond.
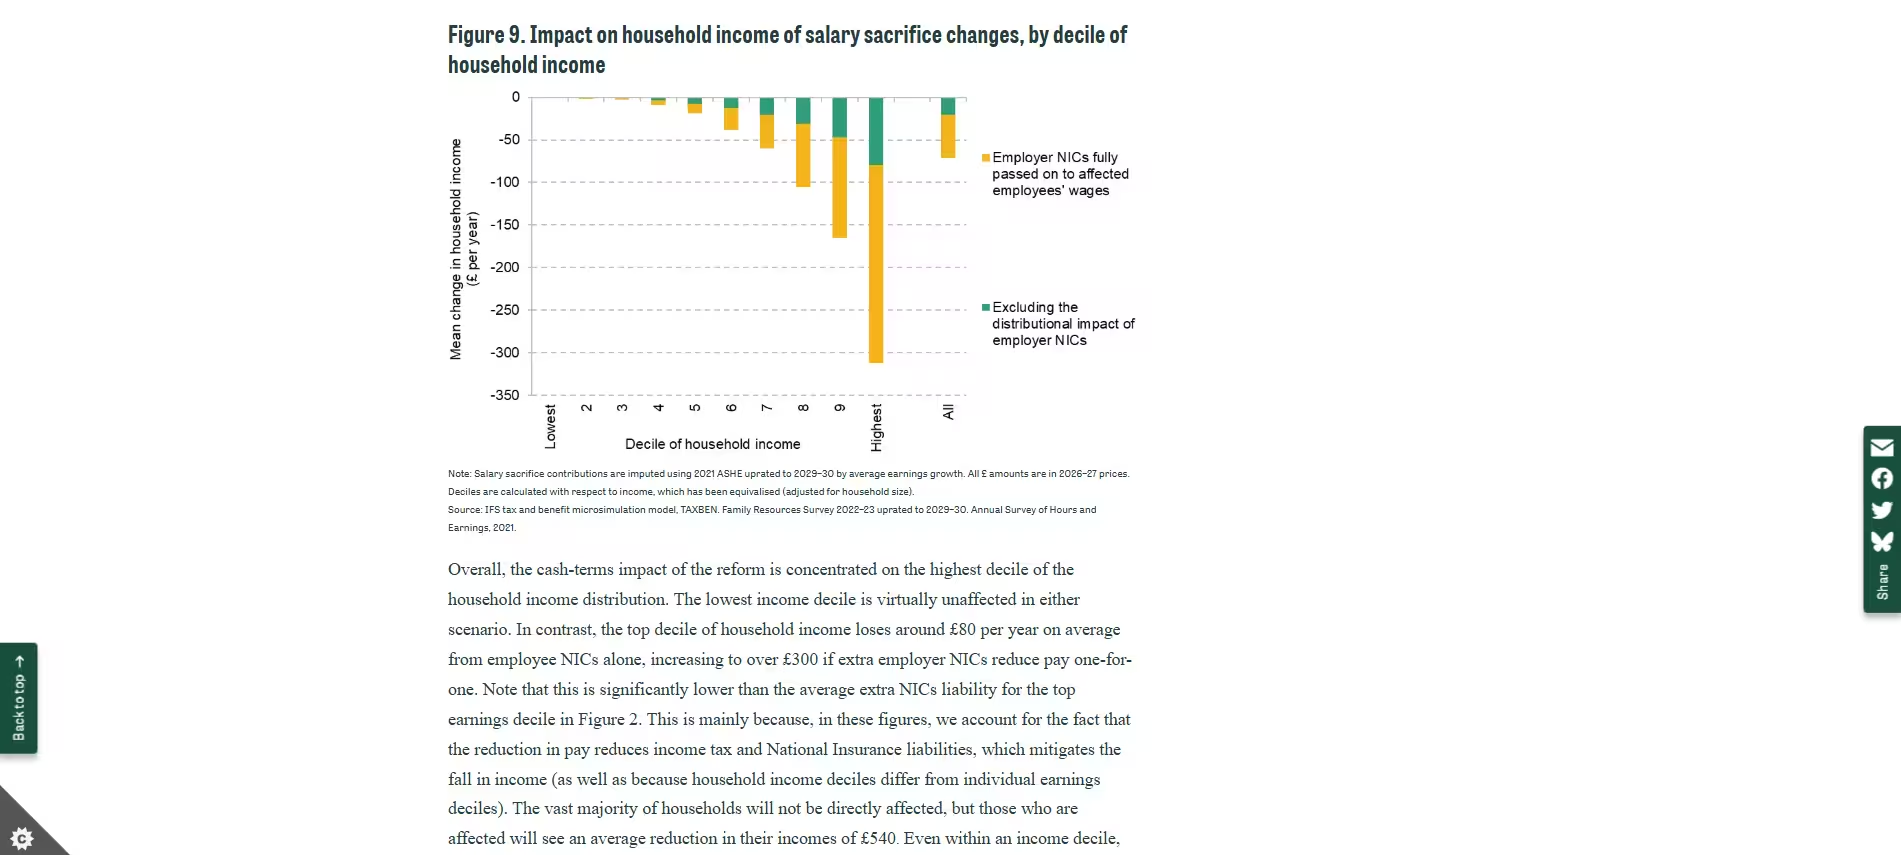
Institute for Fiscal Studies research showing estimated household income losses from the salary sacrifice reform.
Why Are Private Sector Workers More Exposed?
The IFS identified substantial differences between private and public sector pension arrangements.
Approximately 18% of private sector employees make salary sacrifice contributions exceeding £2,000 annually, compared with 7% of public sector employees.
The research estimated average additional annual employer National Insurance liabilities of £151 per private sector employee and £37 per public sector employee, including workers unaffected by the reform.
Finance, insurance, technology and communications businesses are particularly exposed because salary sacrifice is more common among their employees.
In contrast, many public sector pension schemes primarily use ordinary employer contributions.
The IFS also found that the smallest businesses are less likely to operate salary sacrifice schemes, making their direct exposure relatively limited.
Research economist Matthew Oulton, an author of the IFS report, criticised the reform for creating “another new arbitrary line in the tax system”.
His assessment highlights a wider problem: businesses must navigate another contribution threshold without a comprehensive reform of pension taxation.
What Should Small Businesses Do Before April 2029?
The salary sacrifice changes arrive after the April 2025 increase in employer National Insurance from 13.8% to 15%, alongside a reduction in the secondary earnings threshold.
Businesses already operating with narrow margins may therefore need to reassess employment costs.
Practical preparations include:
- Audit existing pension arrangements: Identify employees using salary sacrifice and calculate annual contributions above £2,000.
- Forecast additional costs: Model the employer NI liability under current assumptions.
- Review alternative arrangements: Compare salary sacrifice with net pay and relief-at-source pension contributions.
- Assess ordinary employer contributions: Explore whether direct employer contributions outside salary sacrifice are commercially appropriate.
- Review bonus sacrifice arrangements: Consider how bonuses exchanged for pensions will be treated.
- Consult payroll and employment specialists: Check contracts, employee consultation requirements and payroll software capabilities.
Businesses should not assume that changing pension arrangements automatically eliminates costs. Alternative structures can affect employee income, contractual rights and existing workplace pension obligations.
Does the Pension Tax Raid Affect Limited Company Directors?
Not every company director will be affected.
The Institute of Chartered Accountants in England and Wales explains that the £2,000 salary sacrifice limit generally does not apply to ordinary employer pension contributions made outside salary sacrifice.
This distinction is particularly important for owner-managed companies.
A director receiving a modest salary, dividends and pension contributions paid directly by their company may remain outside the new restriction, provided the contributions are genuinely employer-funded rather than exchanged for contractual earnings.
However, a director who formally sacrifices salary or bonuses in exchange for employer pension contributions may be affected.
Company owners should therefore review how pension contributions are documented and accounted for.
The ICAEW technical explanation highlights this distinction.
Will Inherited Pensions Face Inheritance Tax From April 2027?
Yes. Another significant pension change involves bringing most unused pension funds and certain pension death benefits into inheritance tax calculations from 6 April 2027.
The reform was legislated through the Finance Act 2026.
Previously, many unused pension funds could be passed to beneficiaries outside the deceased person’s estate for inheritance tax purposes.
From April 2027, those funds will generally be considered alongside other estate assets.
However, inheritance tax will not automatically apply to every inherited pension.
Existing exemptions, allowances and certain exclusions will remain relevant, including qualifying transfers to spouses or civil partners and exclusions for death-in-service benefits.
For families already considering inheritance tax planning and proposed policy changes, this creates an additional reason to review wills, pension nominations and estate valuations.
HMRC’s inheritance tax technical guidance explains the forthcoming arrangements for personal representatives and pension administrators.
Is the Government Cutting the 25% Tax-Free Pension Lump Sum?
No reduction to the existing tax-free pension lump sum allowance has been announced as of 26 October 2026.
Most eligible savers can ordinarily withdraw up to 25% of their pension tax-free, subject to a standard lump sum allowance of £268,275. Individual protections and circumstances can alter this limit.
Before the November 2025 Budget, reports suggested Rachel Reeves might reduce the allowance, prompting substantial concern among pension savers.
The Treasury subsequently indicated that the allowance would remain unchanged.
The consequences of this uncertainty were significant.
AJ Bell’s September 2026 analysis of Financial Conduct Authority data found tax-free pension withdrawals reached £18.3 billion in 2024/25 and approximately £22 billion in 2025/26.
AJ Bell estimated excess withdrawals of roughly £10 billion around the 2024 Budget and a further £14 billion around the 2025 Budget, compared with its historical benchmark.
Separately, FCA figures showed approximately £91 billion in total pension withdrawals during 2025/26. That larger amount covers broader pension withdrawals, not solely tax-free cash.
AJ Bell chief executive Michael Summersgill warned that speculation surrounding pension taxation had real consequences for savers.
For individuals approaching retirement, withdrawing pension funds prematurely may sacrifice future tax advantages and investment growth.
How Do Frozen Tax Thresholds and State Pension Changes Fit In?
The pension debate extends beyond workplace contributions.
Income tax Personal Allowance and relevant thresholds are frozen until April 2031, including the £12,570 Personal Allowance and the £50,270 higher-rate threshold for England, Wales and Northern Ireland.
As incomes rise, more people can enter higher tax bands without tax rates themselves increasing.
The State Pension triple lock is also changing.
From April 2030, the government plans to replace the existing earnings element with an adjustment that maintains the State Pension’s value relative to earnings over time.
Annual increases will still be at least inflation or 2.5%, whichever is higher.
The changes could matter to people concerned about retirement income shortfalls, particularly self-employed workers and individuals with irregular pension saving histories.
What Is the Timeline for the UK Pension Tax Changes?
| Date | Confirmed change or milestone |
| 6 April 2025 | Employer NI rate increased to 15% |
| 29 April 2026 | Salary sacrifice legislation received Royal Assent |
| 28 October 2026 | John Healey’s first Autumn Budget scheduled |
| 6 April 2027 | Most unused pensions enter inheritance tax calculations |
| 6 April 2029 | £2,000 salary sacrifice NI exemption limit begins |
| April 2030 | Adjusted State Pension triple lock planned |
| April 2031 | Current income tax threshold freeze ends |
The timeline demonstrates that different reforms will affect retirement planning at different stages.
Could John Healey Reverse the Pension Tax Raid in His October Budget?
John Healey became Chancellor on 20 July 2026 after Rachel Reeves left the role.
His first Budget is scheduled for Wednesday, 28 October 2026.
The change in Chancellor does not automatically cancel legislation introduced by the previous administration.
Consequently, the salary sacrifice restriction and inheritance tax provisions remain scheduled to take effect unless Parliament changes the law.
The Budget could clarify implementation details or introduce additional pension measures.
Areas worth monitoring include the treatment of tax-free pension cash, inheritance tax implementation and employer pension incentives.
However, speculation should not be mistaken for a confirmed announcement.
The House of Commons Library’s Autumn Budget 2026 briefing provides official parliamentary background ahead of the statement.
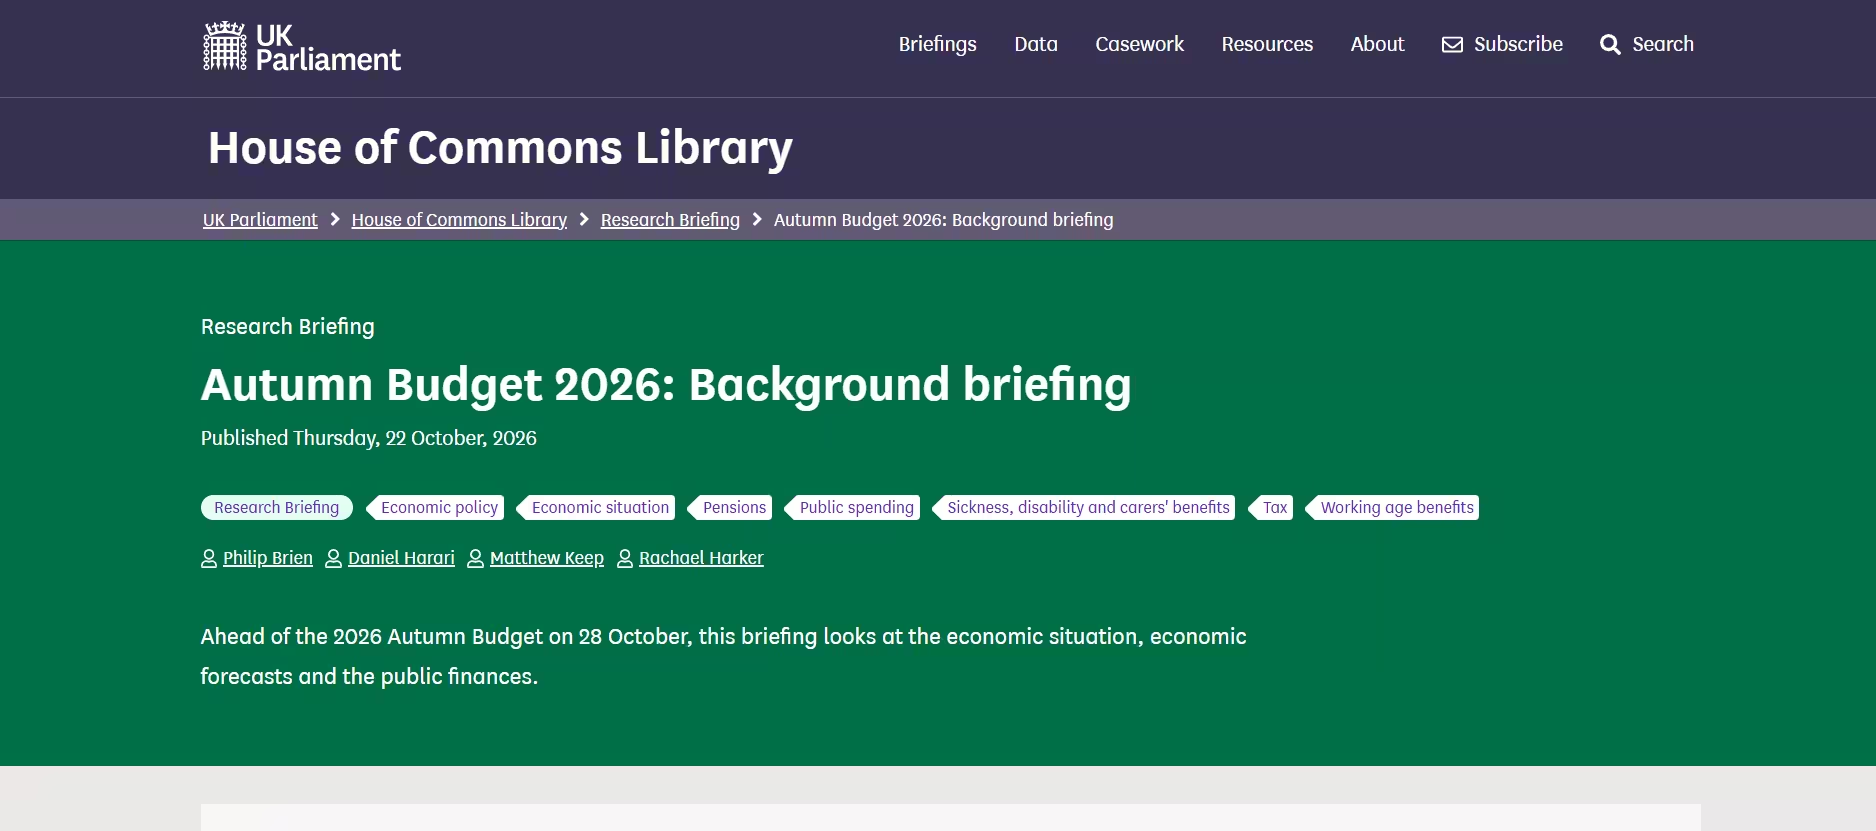
House of Commons Library confirmation of the 28 October 2026 Autumn Budget under Chancellor John Healey.
Conclusion
The Rachel Reeves pension tax raid represents a significant change to workplace pension National Insurance treatment, but it does not remove the fundamental income tax advantages of saving for retirement.
The legislation is already in place, and John Healey’s appointment has not changed its scheduled April 2029 implementation.
For small businesses, the immediate priority is understanding salary sacrifice exposure and forecasting additional payroll costs.
For employees and company directors, the focus should be on reviewing pension arrangements, avoiding rushed withdrawals and distinguishing confirmed changes from Budget speculation.
Frequently Asked Questions
Does the £2,000 Cap Apply to All Employer Pension Contributions?
No. It applies to qualifying pension contributions made through salary sacrifice. Ordinary employer contributions made outside these arrangements remain exempt from National Insurance.
Is the Pension Tax Raid Still Happening Under John Healey?
Yes. The relevant legislation remains in place as of 26 October 2026, with the salary sacrifice change scheduled for April 2029.
Will Company Directors Have to Pay Additional National Insurance?
Only where the relevant salary sacrifice arrangements apply. Genuine employer-funded pension contributions outside salary sacrifice are treated differently.
Should Employees Increase Pension Contributions Before April 2029?
That depends on individual circumstances. Employees should consider affordability, pension allowances and future retirement needs rather than increasing contributions solely because of anticipated tax changes.
Will the Government Remove Pension Income Tax Relief?
The confirmed salary sacrifice reform changes National Insurance treatment. Existing income tax relief on qualifying pension contributions remains in place.
Are All Inherited Pensions Subject to Inheritance Tax From 2027?
No. Most unused funds enter estate calculations, but tax depends on the estate’s circumstances, applicable allowances and exemptions.
Can Employers Stop Offering Salary Sacrifice Pensions?
Employers may review or replace arrangements, but changes can involve contractual obligations, employee consultation and workplace pension compliance requirements.
Jennifer contributes business-focused articles covering modern business trends, digital growth, entrepreneurship, and practical insights designed to support startups and SMEs.
UK Budget Savings Tax Changes 2026: New Rates, ISA Rules and How Much More Savers Could Pay?
The UK Budget savings tax changes announced on 28 October 2026 have introduced significant financial implications for millions of savers, pensioners and small business owners. From 6 April…
DWP Energy Bill Letters Dispatched: Six Million Households Could Get £150 Discount
Millions of UK households are being urged to watch their post as the Department for Work and Pensions (DWP) prepares to distribute letters concerning a £150 reduction in…
Insights for the Modern
UK Small Business.
Join 15,000+ owners receiving tactical analysis on finance, marketing, and technology. No clutter.
Zero spam. Unsubscribe in one click.