Why Has My Tax Code Changed From 1250L to 1185L?
Tax guidance: Checked against published HMRC guidance. Independent review by a qualified UK tax professional should be completed before publication.
If your tax code has changed from 1250L to 1185L, HM Revenue & Customs (HMRC) has reduced the tax-free allowance used to calculate Income Tax on your wages or pension by £650.
This usually happens because of taxable workplace benefits, unpaid tax from an earlier year, additional income, savings interest or changes to your pension.
However, there is an important detail many taxpayers overlook: 1250L was not the standard tax code in 2026/27. The standard code for most employees with one job and no adjustments is 1257L, representing a £12,570 Personal Allowance.
Your previous code therefore already contained a £70 reduction. Moving to 1185L increases the total reduction from the standard allowance to £720.
Understanding this difference is essential when checking whether HMRC has calculated your tax correctly.
Why Has the Tax Code Changed From 1250L to 1185L?
A change from 1250L to 1185L means the tax-free amount allocated to your PAYE income has fallen from £12,500 to £11,850.
| Tax code | Tax-free amount | Difference from 1257L |
| 1257L | £12,570 | Standard allowance |
| 1250L | £12,500 | £70 lower |
| 1185L | £11,850 | £720 lower |
The difference between your old and new codes is £650.
For someone whose additional taxable income falls entirely within the 20% tax band, this represents approximately £130 more Income Tax over a full tax year. At 40%, the equivalent is £260.
It does not necessarily mean you owe HMRC £650.
Your individual PAYE coding notice should explain the actual adjustment.
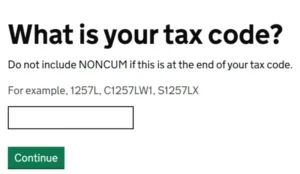
GOV.UK’s official tax-code checker, showing where employees can enter a code to understand its meaning.
What Do Tax Codes 1250L and 1185L Mean?
UK tax codes tell employers and pension providers how to calculate Income Tax deductions under Pay As You Earn (PAYE).
For ordinary codes ending in L, multiplying the numerical portion by ten generally gives the annual tax-free amount allocated to that source of income.
For example:
- 1257L represents £12,570.
- 1250L represents £12,500.
- 1185L represents £11,850.
The letter L indicates entitlement to the standard type of Personal Allowance, although the amount available through a particular PAYE code may have been adjusted.
This distinction matters because a code does not always represent your complete tax position. Someone with two jobs, pensions or untaxed income may have allowances and deductions distributed across different income sources.
Why Were You on 1250L in the First Place?
The standard Personal Allowance for 2026/27 is £12,570, so a previous code of 1250L suggests HMRC had already incorporated an adjustment.
Possible explanations include a small taxable benefit, estimated untaxed income, an earlier PAYE correction or the allocation of allowances between income sources.
For example, a £70 deduction from the standard £12,570 allowance would produce £12,500, represented by 1250L.
If HMRC subsequently applies a further £650 deduction, the available amount becomes £11,850.
Your revised code would then be 1185L.
However, this is only an illustrative calculation. The actual code can reflect several additions and deductions, so compare both coding notices rather than assuming the entire £650 relates to one new expense.
Has the Government Reduced the Personal Allowance?
No. The standard UK Personal Allowance remains £12,570 for 2026/27 and is scheduled to stay frozen until 5 April 2031.
The freeze can increase tax pressure when wages rise because more income may move into taxable bands, a phenomenon known as fiscal drag.
Nevertheless, an individual change from 1250L to 1185L is not evidence that the Government has cut everyone’s Personal Allowance.
How to Decode the £650 Reduction in Your Tax Code?
The most useful way to investigate your revised code is to identify what financial adjustment could produce a £650 reduction.
Several different circumstances can produce the same numerical result.
1. A £650 Taxable Workplace Benefit
Suppose your employer provides private medical insurance with a taxable annual value of £650.
If HMRC collects the tax through a coding adjustment, rather than through payroll taxation of the benefit, it may reduce your available tax-free allowance by approximately £650.
Similar adjustments can arise from company cars, employer-provided accommodation or other taxable benefits.
Check whether your employer already taxes the benefit through payroll. You should not assume an additional deduction is correct if the tax is already being collected elsewhere.
2. £650 of Untaxed Income
HMRC can adjust tax codes to collect Income Tax on income that has not been taxed at source.
Examples include certain rental profits, additional earnings and taxable savings interest.
Suppose HMRC estimates £650 of taxable income that will not otherwise be taxed or declared through another collection arrangement.
A corresponding £650 restriction may arise in a straightforward case.
However, £650 of savings interest does not automatically mean £650 is taxable.
Many taxpayers have a Personal Savings Allowance. For 2026/27, this is generally £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and zero for additional-rate taxpayers. The starting rate for savings may also apply.
3. £130 of Previously Underpaid Tax
This is one of the most important distinctions.
HMRC does not ordinarily reduce your tax-free allowance pound for pound by the amount of tax you owe.
Instead, it calculates a coding restriction intended to recover the tax at the rate applicable to your PAYE income.
For example:
£130 ÷ 20% = £650
Therefore, £130 of tax owed can generate a £650 allowance restriction where that income is taxed at 20%.
For a taxpayer whose relevant income is taxed at 40%:
£260 ÷ 40% = £650
Both examples produce the same £650 coding restriction.
HMRC’s PAYE Manual, under reference PAYE12080, confirms that underpayment restrictions reflect the applicable tax rate and that additional calculations apply when multiple tax bands are involved.
These examples are simplified; an actual restriction can differ where HMRC uses more than one rate or other coding limits apply.
4. Could Marriage Allowance Explain £650?
Marriage Allowance can change your tax code, but it does not ordinarily explain this exact reduction on its own.
For 2026/27, eligible married couples and civil partners can transfer £1,260 of Personal Allowance.
HMRC normally uses:
- M for the person receiving the transferred allowance.
- N for the person transferring their allowance.
Because the standard transfer is £1,260, a standalone £650 reduction is not the normal Marriage Allowance adjustment.
Check whether Marriage Allowance has been combined with another deduction before dismissing it entirely.
Other Reasons HMRC May Change Your Tax Code
HMRC can revise your code without your employer changing your salary.
Common triggers include the following.
Company Benefits and Employment Changes
A new company car, medical policy or other taxable benefit may affect the tax due on your employment.
Starting a second job can also change how HMRC allocates your Personal Allowance.
Your main employment may retain most or all of the allowance, while a second job receives a BR or another rate-based code.
If an old employer remains incorrectly listed, HMRC may calculate deductions using outdated information.
State Pension and Private Pension Income
State Pension income is taxable, but tax is not normally deducted before the pension is paid.
HMRC may therefore collect tax through another PAYE income source.
An increase in your weekly State Pension can also change your tax code even when your employment remains unchanged.
This issue is particularly relevant to retirees because frozen thresholds and increasing pension payments can affect their overall liability.
The challenges are explored further in the discussion of HMRC’s State Pension tax calculation problems.
High Income Child Benefit Charge
The High Income Child Benefit Charge may apply when an individual’s adjusted net income exceeds £60,000 and they or their partner receive Child Benefit.
The charge increases as income rises and generally reaches the full Child Benefit amount at £80,000 or more.
Eligible taxpayers can arrange to pay through PAYE, which can result in a revised tax code.
If you already pay through Self Assessment, check that you are not inadvertently accounting for the same liability twice.
Winter Fuel Payment Repayments
HMRC may also change PAYE codes to recover Winter Fuel Payments or Scotland’s Pension Age Winter Heating Payments.
For 2026/27, this can affect eligible recipients whose total annual income exceeds £35,000, subject to relevant exemptions.
The repayment is a separate tax charge, rather than ordinary taxation of the payment as income.
Tax Relief on Employment Expenses
Not every tax-code change means you will pay more.
If HMRC approves a claim for qualifying employment expenses, professional subscriptions or other eligible tax relief, your available tax-free allowance may increase.
A previously included relief that has ended or changed can have the opposite effect.
Checking both additions and deductions on your coding notice is therefore important.
How Much Extra Tax Will You Pay With 1185L?
The financial impact depends on your marginal Income Tax rate and how much of the additional £650 falls within each tax band.
The following table assumes the entire £650 difference is taxed at one rate for a complete tax year.
| Income Tax rate | Extra annual tax | Monthly average |
| 19% | £123.50 | £10.29 |
| 20% | £130.00 | £10.83 |
| 21% | £136.50 | £11.38 |
| 40% | £260.00 | £21.67 |
| 42% | £273.00 | £22.75 |
| 45% | £292.50 | £24.38 |
| 48% | £312.00 | £26.00 |
For taxpayers in England, Wales and Northern Ireland, the principal employment income rates in 2026/27 are 20%, 40% and 45%.
Scotland has six employment income bands, including rates of 19%, 20%, 21%, 42%, 45% and 48%.
These figures are budgeting estimates, not guaranteed payslip deductions.
A mid-year change applied cumulatively can generate a larger adjustment in one payslip because PAYE considers tax already deducted earlier in the year.
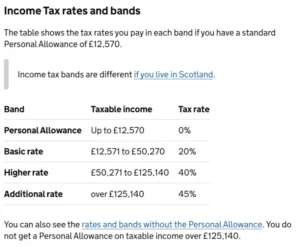
Official 2026/27 Income Tax bands showing why the same tax-code reduction produces different costs.
Simple Tax Code Change Calculator
You can estimate the annual impact yourself using:
Step 1: Subtract your new code’s allowance from the previous allowance.
£12,500 − £11,850 = £650
Step 2: Convert your applicable marginal tax rate into a decimal.
20% = 0.20; 40% = 0.40.
Step 3: Multiply the allowance difference by the tax rate.
£650 × 0.20 = £130 annually.
Step 4: Divide by 12 for a simple monthly budget.
£130 ÷ 12 = £10.83.
For a basic-rate employee, reserving approximately £11 extra each month may be sensible until the revised payslip confirms the actual deduction.
This calculator does not model cumulative PAYE, crossing tax bands, the £100,000 taper or other individual adjustments.
Does an 1185L Code Work Differently in Scotland and Wales?
Yes. The numerical meaning may be similar, but the tax calculations depend on where you are resident for Income Tax purposes.
Scotland: S1185L
A Scottish taxpayer may receive S1185L.
The S prefix indicates that Scottish Income Tax rates apply to relevant employment and pension income.
Scotland also uses codes including SBR, SD0, SD1, SD2 and SD3 for income taxed at specific Scottish rates, often associated with additional jobs or pensions.
Importantly, Scottish savings interest and dividend income generally follow UK-wide rather than Scottish employment income rates.
Wales: C1185L
Welsh taxpayers may receive C1185L.
The C prefix identifies them as Welsh taxpayers.
For 2026/27, Welsh employment Income Tax rates remain aligned with those in England and Northern Ireland, although the identification remains important for PAYE administration.
Neither S nor C automatically indicates a tax problem.
The correct prefix depends on your tax residence, rather than simply where your employer operates.
What Do Emergency Tax Codes Mean?
Emergency codes commonly appear when employers do not yet have complete information about previous employment, earnings or tax paid.
You may see:
| Code suffix | Meaning |
| W1 | Week 1 emergency calculation |
| M1 | Month 1 emergency calculation |
| X | Non-cumulative emergency calculation |
| NONCUM | Payroll description for non-cumulative treatment |
For example, 1185L M1 is different from a normal cumulative 1185L code.
Emergency treatment usually calculates tax using the current pay period without fully considering previous earnings and deductions in the tax year.
It can therefore produce an unexpected tax deduction.
An emergency code following a new job is often temporary. HMRC normally updates it after obtaining the necessary employment information.
However, some emergency arrangements associated with company benefits, State Pension changes or outstanding tax can remain until the end of the tax year.
If a new employer does not have your previous information, provide your P45 or complete the relevant starter checklist.
What About BR, D0, 0T and K Codes?
BR generally taxes all relevant income at the basic rate, while D0 applies the higher rate in England, Wales and Northern Ireland.
A 0T code gives no Personal Allowance against that income source.
K codes apply when deductions or income being accounted for exceed the available allowances.
For example, the State Pension and taxable benefits may produce deductions greater than someone’s Personal Allowance.
A K code adds an amount to taxable pay for PAYE purposes, subject to specific limits on the tax that payroll can deduct.
These codes require different calculations from the ordinary L-code examples.
Can Income Above £100,000 Change Your Tax Code?
Yes. Taxpayers whose adjusted net income exceeds £100,000 are subject to the Personal Allowance taper.
For every £2 above £100,000, the allowance is reduced by £1.
For example:
| Adjusted net income | Standard Personal Allowance remaining |
| £100,000 | £12,570 |
| £105,000 | £10,070 |
| £110,000 | £7,570 |
| £125,140 | £0 |
At £125,140 or above, the standard Personal Allowance is completely withdrawn.
Pension contributions and Gift Aid donations can affect adjusted net income, so gross salary alone may not tell the whole story.
HMRC may initially use estimated earnings when adjusting PAYE codes. Employees expecting large bonuses or significant income fluctuations should compare those estimates with their realistic annual earnings.
How Can You Check Whether Your 1185L Tax Code Is Correct?
The most reliable starting point is HMRC’s official online service rather than estimating the reason from your payslip alone.
Use the Check your Income Tax for the current year service.
You can inspect your tax code, estimated employment earnings, pension income and relevant changes recorded by HMRC.
Step 1: Find Your Current Tax Code
Check your latest payslip, HMRC app or Personal Tax Account.
Confirm whether the code is simply 1185L or includes a prefix or emergency suffix.
Step 2: Examine Your PAYE Coding Notice
Your P2 notice explains how HMRC calculated the code.
Look for company benefits, untaxed income, tax underpayments, pension amounts and other deductions.
Compare the notice for 1250L with the one showing 1185L.
The objective is to establish exactly which item accounts for the £650 movement.
Step 3: Verify the Figures
Compare HMRC’s records against your P45, P60, payslips, benefit statements, bank interest information and pension correspondence.
Check whether an employer or income source is duplicated or out of date.
Step 4: Correct Inaccurate Information
Use HMRC’s online service to update eligible employment, pension or income details.
For employer-reported benefits, contact payroll or your employer if the source information is wrong.
Neela Chauhan, a partner at accountancy firm UHY Hacker Young, emphasised the importance of taxpayers reviewing their tax codes and year-end PAYE calculations in published January 2026 reporting.
Her comments highlight a practical issue: outdated estimates of benefits or additional income can remain unnoticed when employees assume their payroll deductions must be correct.
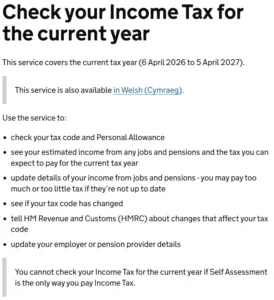
GOV.UK’s Check your Income Tax service, where taxpayers can review their current code and estimated earnings.
How Long Does HMRC Take to Correct a Tax Code?
According to HMRC’s published guidance, after you update information and HMRC changes your tax code, it should notify you and your employer of the new code within 15 working days.
Once the revised code has been issued:
- Monthly employees should normally see it on their next or following payslip.
- Weekly employees should normally see it by their third payslip.
If it does not appear, ask your employer whether the updated code has been received and applied.
For someone who has recently started a job, HMRC advises allowing 35 days for employment information to be processed before contacting them about a suspected error.
These times describe HMRC’s published process, not a guarantee that every complex tax dispute will be fully resolved within 15 working days.
Can You Receive a Refund After an Incorrect Tax Code?
Yes. If an incorrect code caused excessive Income Tax deductions, HMRC may arrange a refund once the correct liability has been established.
During the tax year, a corrected cumulative code can sometimes result in an adjustment through your wages or pension.
After the tax year, HMRC may reconcile your records and issue a calculation showing whether you overpaid or underpaid tax.
Employees should distinguish genuine HMRC correspondence from unexpected refund messages requesting bank details.
The article on HMRC £473 payment letters and tax refunds explains how PAYE repayments can differ from Self Assessment refunds.
Does Having a Side Business Affect Your PAYE Tax Code?
It can, particularly where HMRC estimates taxable income outside employment and collects tax through PAYE.
For example, someone with full-time employment and freelance earnings may need to account for business profits separately.
However, having PAYE deductions adjusted does not automatically remove a requirement to register for or submit Self Assessment.
Taxpayers starting freelance activities should check the HMRC registration requirements for sole traders rather than relying solely on their employment tax code.
If the same income appears in both PAYE estimates and Self Assessment records, establish how HMRC intends to collect the tax before requesting changes.
Frequently Asked Questions
Is 1185L the correct tax code for 2026/27?
It can be correct if HMRC has calculated adjustments reducing the available allowance to £11,850. However, the standard code for most people with one job and no adjustments is 1257L.
Why did my tax code change when my salary stayed the same?
HMRC may have received updated benefit information, savings interest figures, pension details or previous-year tax calculations. Your salary does not need to change for your PAYE code to change.
Does 1185L mean I owe HMRC £650?
No. £650 is the reduction in the tax-free amount between 1250L and 1185L. A smaller actual tax debt, such as £130 at 20%, could generate this coding restriction.
Can savings interest change my tax code?
Yes. Interest exceeding applicable tax-free allowances can generate additional Income Tax, which HMRC may collect through PAYE.
Can getting married change my tax code?
Marriage itself does not automatically produce a change. A successful Marriage Allowance claim can change the codes of eligible spouses or civil partners.
Can Child Benefit affect my tax code?
Yes. Eligible individuals paying the High Income Child Benefit Charge through PAYE may receive adjusted tax codes.
Is 1185L an emergency tax code?
Not by itself. It is normally an ordinary cumulative code unless accompanied by an emergency indicator such as W1, M1, X or NONCUM.
Can I change my tax code through my employer?
Your employer can correct inaccurate payroll information but ordinarily cannot independently replace a tax code issued by HMRC. The correct code must be obtained through the applicable PAYE process.
Will a corrected tax code refund overpaid Income Tax?
It can. A corrected cumulative code may adjust tax through payroll, while other cases require HMRC reconciliation or a separate repayment.
Should I contact HMRC immediately after changing jobs?
HMRC generally advises waiting 35 days for new employment information to be processed before contacting it about an incorrect code.
John covers a wide range of business topics including technology, productivity, startups, digital transformation, and business development for modern companies.
UK Budget Savings Tax Changes 2026: New Rates, ISA Rules and How Much More Savers Could Pay?
The UK Budget savings tax changes announced on 28 October 2026 have introduced significant financial implications for millions of savers, pensioners and small business owners. From 6 April…
DWP Energy Bill Letters Dispatched: Six Million Households Could Get £150 Discount
Millions of UK households are being urged to watch their post as the Department for Work and Pensions (DWP) prepares to distribute letters concerning a £150 reduction in…
Insights for the Modern
UK Small Business.
Join 15,000+ owners receiving tactical analysis on finance, marketing, and technology. No clutter.
Zero spam. Unsubscribe in one click.