I Have Never Paid National Insurance – Will I Get A Pension In 2026?
Yes. If you have never personally paid National Insurance, you may still be entitled to a UK State Pension.
What matters is the number of qualifying years on your National Insurance record, rather than simply whether National Insurance was deducted from your wages.
Qualifying years can come from:
- National Insurance Contributions Paid Through Employment
- National Insurance Credits For Parents, Carers And Certain Benefit Claimants
- Years Where You Were Treated As Having Paid NI
- Eligible Self-Employed Years
- Voluntary National Insurance Contributions
- Certain Periods Of Work Or Contributions Abroad
Under the new State Pension, you normally need at least 10 qualifying years to receive any State Pension. If your National Insurance record started after April 2016, you would normally need 35 qualifying years to receive the full new State Pension.
For 2026/27, the full new State Pension is £241.30 a week, equivalent to £12,547.60 over 52 weeks.
The first thing to do if you think you have never paid National Insurance is to check your State Pension forecast on GOV.UK.
The service can show how much State Pension you could receive, when you can claim it and whether you may be able to increase your entitlement.
You should also check your National Insurance record because you may already have qualifying years from credits or other circumstances without realising it.
How Many Qualifying Years Do You Need For A State Pension In 2026?
Under the new State Pension system, most people need at least 10 qualifying years on their National Insurance record before they can receive any new State Pension.
Those 10 years do not normally have to be consecutive.
If your National Insurance record began after 6 April 2016, you will generally need 35 qualifying years for the full new State Pension.
The calculation is more complicated if you built up National Insurance contributions before April 2016. Transitional rules,
Additional State Pension entitlement and periods when you were contracted out can all affect the amount you receive. Some people may therefore need more than 35 qualifying years to reach the full new State Pension rate.
What Counts As A Qualifying Year?
A qualifying year can be created in several ways. It is not limited to years when you physically paid National Insurance.
A year may count when you:
- Worked And Paid National Insurance
- Earned Enough To Be Treated As Having Paid NI
- Received Eligible National Insurance Credits
- Were Self-Employed And Met The Relevant Conditions
- Paid Voluntary National Insurance
- Had Eligible Contributions Or Periods Abroad
This distinction is particularly important for stay-at-home parents, carers, low-paid workers and people with periods outside employment.
What Happens If You Have Fewer Than 10 Years?
If you are covered by the new State Pension and reach State Pension age with fewer than 10 qualifying years, you will normally not receive a new State Pension based solely on that UK record.
However, you should not assume you have fewer than 10 years simply because you remember working for less than 10 years.
Your record may contain credits from periods when you were:
- Looking After Children
- Caring For Someone
- Unemployed And Receiving An Eligible Benefit
- Unable To Work Due To Illness
- Receiving Universal Credit
- Building Qualifying Years Through Self-Employment
Certain overseas contributions can also affect whether you meet the minimum qualifying conditions.
How Much State Pension Could You Get In 2026/27?
The full new State Pension for 2026/27 is £241.30 a week.
For someone whose National Insurance record started after April 2016, each qualifying year generally represents 1/35 of the full rate until the maximum is reached.
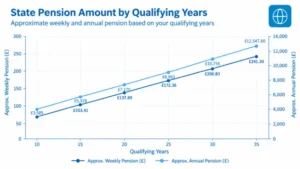
A simplified illustration looks like this:
| Qualifying Years | Approx. Weekly Pension | Approx. Annual Pension |
| 10 | £68.94 | £3,585 |
| 15 | £103.41 | £5,378 |
| 20 | £137.89 | £7,170 |
| 25 | £172.36 | £8,963 |
| 30 | £206.83 | £10,755 |
| 35 | £241.30 | £12,547.60 |
These figures are illustrations rather than personal pension forecasts.
People with National Insurance histories before April 2016 may receive a different amount because the government uses transitional calculations. Contracted-out employment and Additional State Pension entitlement can also change the result.
Checking your State Pension forecast is therefore more reliable than calculating your pension simply by dividing the full rate by 35.
Can You Build Qualifying Years Without Actually Paying National Insurance?
Yes, and this is one of the most important points for anyone asking, “I have never paid National Insurance, will I get a pension?”
It is possible for a year to count towards your State Pension even when you did not personally hand over National Insurance contributions.
For employees in 2026/27, someone earning between £129 and £242 a week from one job does not normally pay employee National Insurance but can still be treated as having paid contributions.
This means a low-paid employee could look at their payslips, see no National Insurance deduction and assume they are building no State Pension entitlement. That assumption may be wrong.
NI Credits For Parents, Carers, Illness And Unemployment
National Insurance credits can protect your record when circumstances prevent you from working or paying contributions.
Credits may be available in circumstances including:
- Receiving Child Benefit For A Child Under 12
- Receiving Carer’s Allowance
- Providing Eligible Unpaid Care
- Receiving Universal Credit
- Receiving Certain Unemployment Benefits
- Receiving Certain Sickness Or Disability Benefits
- Receiving Maternity Allowance
- Certain Periods Of Parental Pay
Some credits are awarded automatically, while others have to be claimed.
That makes checking your actual National Insurance record important. Do not assume that a period away from work either automatically counts or automatically does not count.
Child Benefit And Specified Adult Childcare Credits
A parent or guardian registered for Child Benefit for a child under 12 can normally receive Class 3 National Insurance credits automatically.
This can protect State Pension entitlement even if the parent does not work.
Importantly, a person can still protect their National Insurance record by registering for Child Benefit even in circumstances where they decide not to receive Child Benefit payments.
There are also Specified Adult Childcare Credits.
These may be available where an eligible family member, such as a grandparent, cares for a child under 12 and the child’s parent or guardian agrees to transfer unused credits.
This can be particularly valuable for grandparents who give up work or reduce their hours to provide childcare.
What If You Have Never Worked?
Never having had a paid job does not automatically mean you will receive no State Pension.
Consider someone who spent many years at home bringing up children.
If they were registered for Child Benefit while the children were under 12, those years may have generated National Insurance credits even though the parent never had National Insurance deducted from wages.
The same principle can apply to carers and people receiving certain benefits.
However, if you have genuinely:
- Never Worked
- Never Received Qualifying NI Credits
- Never Paid Voluntary Contributions
- Never Built Qualifying Years Through Another Route
you may not have enough qualifying years to receive a State Pension.
Your National Insurance record provides the clearest answer.
Could You Be Missing National Insurance Credits From Previous Years?
Historic gaps deserve particular attention if you spent time raising children.
Before National Insurance credits for parents and carers were introduced in their current form from April 2010, a system called Home Responsibilities Protection, or HRP, helped protect the State Pension records of some parents and carers.
Some historic records have contained missing HRP, including cases involving older Child Benefit claims.
If you were a parent or carer before April 2010 and your National Insurance record shows unexpected gaps, do not immediately assume those years are permanently lost.
Check whether:
- You Received Child Benefit During The Period
- The Child Benefit Claim Was In Your Name
- Your National Insurance Number Was Correctly Recorded
- Home Responsibilities Protection Should Have Applied
- Your Record Can Be Corrected
It is particularly important for couples to check which person’s name was attached to the Child Benefit claim, as the credits may not always appear on the record of the person who actually stayed at home caring for the child.
What If You Are Self-Employed And Have Not Paid National Insurance?
Self-employed workers have another reason not to judge their State Pension position simply by looking at how much National Insurance they physically paid.
For 2026/27, if your self-employed profits are £7,105 or more, Class 2 National Insurance is generally treated as having been paid to protect your National Insurance record.
You do not physically pay Class 2 in these circumstances.
If your profits are below £7,105, you do not normally have to pay Class 2, although eligible people may choose to make voluntary Class 2 contributions.
This is especially relevant for sole traders with low or irregular profits.
Someone may therefore be able to say accurately, “I did not actually pay Class 2 National Insurance”, while still having qualifying years recorded for State Pension purposes.
How To Check Your National Insurance Record And State Pension Forecast?
Checking your records should come before deciding whether you need to pay anything.
Your National Insurance record can show:
- Years That Are Already Complete
- National Insurance Contributions
- National Insurance Credits
- Incomplete Years
- Gaps That May Be Fillable
- Years Where Voluntary Contributions May Be Possible
You should also check your State Pension forecast.
The two services provide different information.
Your National Insurance record shows what has been recorded against individual tax years.
Your pension forecast estimates how much State Pension you could receive, when you can receive it and whether increasing your record could increase your pension.
This is particularly useful before paying voluntary contributions because not every gap needs to be filled.
State Pension age is also gradually increasing from 66 to 67 between 2026 and 2028, so the exact age at which you can claim depends on your date of birth.
Can You Pay Voluntary National Insurance To Increase Your Pension?
If you have gaps in your National Insurance record, you may be able to fill some of them by paying voluntary contributions.
For 2026/27, the standard voluntary Class 3 rate is £18.40 a week.
Where someone is eligible to pay voluntary Class 2 contributions, the 2026/27 rate is £3.65 a week.
A full year of Class 3 at £18.40 a week would cost around £956.80, although the actual amount required depends on how much of the particular year is missing and which rate applies.
How Far Back Can You Fill Gaps?
Under the normal rules, voluntary National Insurance contributions can generally be paid for the previous six tax years.
The deadline is normally 5 April each year.
For example, a gap relating to the 2025/26 tax year can normally be filled until 5 April 2032.
The special extended deadline that once allowed many people to fill much older gaps ended in April 2025, so older articles referring to that concession should not be treated as current guidance.
When Paying Voluntary NI May Not Be Worth It?
Do not automatically pay every gap displayed on your record.
Voluntary contributions do not always increase a person’s State Pension.
Before paying, consider:
- How Many Qualifying Years You Already Have
- How Many Years Remain Before State Pension Age
- Whether You Are Likely To Build More Years Naturally
- Whether The Particular Gap Increases Your Forecast
- Whether You Can Claim NI Credits Instead
- Whether You Have A Pre-2016 Contribution History
- Whether Overseas Contributions Affect Your Position
For a straightforward post-2016 record, one additional qualifying year could represent roughly £6.89 a week at the 2026/27 full rate, provided that year actually increases the person’s entitlement.
For someone close to retirement, filling a useful gap can therefore provide considerably more pension over time than the cost of the contribution. But the calculation needs to be checked individually.
What If You Have Lived Or Worked Abroad?
Living or working outside the UK does not necessarily mean those years are irrelevant.
Depending on the country and the applicable social security arrangements, periods of insurance or contributions abroad may help someone satisfy the minimum qualifying conditions for the UK State Pension.
However, overseas periods do not necessarily increase the amount of UK State Pension in the same way as a complete UK qualifying year.
There was also an important change from 6 April 2026.
For periods abroad from 2026/27 onwards, voluntary Class 2 National Insurance is generally no longer available.
People applying to pay voluntary Class 3 contributions for periods abroad are normally subject to stronger UK connection requirements.
Broadly, this can involve having previously lived in the UK for 10 continuous years or having 10 years of qualifying National Insurance contributions, although transitional arrangements and social security agreements can affect individual cases.
People with an international work history should therefore check their State Pension forecast before paying voluntary contributions.
Can You Get A State Pension Through Your Spouse Or Civil Partner?
Under the new State Pension, your entitlement is normally based on your own National Insurance record rather than your spouse’s or civil partner’s record.
However, limited exceptions exist.
Some people may be able to inherit or increase State Pension entitlement following the death of a spouse or civil partner.
Older pension rules can also apply differently to people who reached State Pension age before the new system began in April 2016.
If you are relying on a spouse’s contribution history rather than your own, it is important to check which State Pension system applies to you instead of assuming their NI record automatically gives you a pension.
What Happens If You Reach State Pension Age With Little Or No State Pension?
Having insufficient qualifying years for a full State Pension does not necessarily mean you will have no retirement income.
You may still have:
- A Workplace Pension
- A Personal Pension
- Savings Or Investments
- Income From Employment
- Income From A Partner
- Eligibility For Means-Tested Support
Could You Qualify For Pension Credit?
Pension Credit is separate from the State Pension.
It is an income-related benefit for eligible people who have reached State Pension age.
For 2026/27, Guarantee Credit can top qualifying weekly income to £238 for a single person or £363.25 for a couple.
These figures are not automatic payments. Pension Credit considers household circumstances and income from sources including pensions and earnings.
Someone receiving little or no State Pension may qualify, but having no State Pension does not automatically guarantee Pension Credit. Equally, receiving some State Pension does not necessarily prevent a claim.
What Should You Do If You Have Never Paid National Insurance?
If you are unsure whether you will receive a pension, take the following steps in order:
- Check Your National Insurance Record: Find out how many complete qualifying years you actually have.
- Look For National Insurance Credits: Review periods involving children, caring, unemployment, illness or eligible benefits.
- Check Historic Child Benefit Records: Look for missing Home Responsibilities Protection or NI credits where appropriate.
- Check Your State Pension Forecast: See your estimated pension and whether it can still be increased.
- Identify Incomplete Years: Find out which gaps are still within the payment deadline.
- Check Whether Credits Can Fill the Gap First: Do not pay voluntary NI for a period that could potentially be credited.
- Check Whether Voluntary Contributions Increase Your Pension: Filling a gap is useful only if it improves your eventual entitlement.
- Review Overseas Contributions: International work history can alter both eligibility and top-up options.
The key point is that having never personally paid National Insurance does not automatically mean you will receive no State Pension. Your complete National Insurance record is what determines the answer.
Conclusion
If you have never paid National Insurance, you may still get a pension in 2026 because qualifying years can be built in several ways.
Parents may have Child Benefit credits, carers may have National Insurance credits, low-paid employees can sometimes be treated as having paid contributions, and self-employed people with profits of at least £7,105 in 2026/27 can have Class 2 treated as paid.
The new State Pension normally requires at least 10 qualifying years, while someone whose record began after April 2016 generally needs 35 years for the full £241.30 weekly rate.
Before assuming you have no pension entitlement or paying to fill missing years, check both your National Insurance record and your State Pension forecast.
They provide a much more accurate picture than simply counting the years in which money was deducted from your wages.
Frequently Asked Questions
Can I Get A State Pension If I Have Never Paid National Insurance?
Yes. You may have qualifying years from National Insurance credits, treated-as-paid contributions, self-employment, voluntary contributions or certain overseas periods.
Can I Get A State Pension If I Have Never Worked?
Potentially. Parents, carers and some benefit claimants can build qualifying years through National Insurance credits even without paid employment.
What Happens If I Have Less Than 10 Years Of National Insurance?
Under the new State Pension, fewer than 10 qualifying years will normally mean you do not receive a new State Pension, although overseas periods and some special rules can affect eligibility.
How Much State Pension Will I Get With 10 Qualifying Years?
For a straightforward record starting after April 2016, 10 years at the 2026/27 full rate works out at roughly £68.94 a week. Pre-2016 records can be calculated differently.
Do Child Benefit Years Count Towards My State Pension?
They can. A parent or guardian registered for Child Benefit for a child under 12 normally receives Class 3 National Insurance credits.
Can I Pay Missing National Insurance Years Before Retirement?
Often yes. You can normally pay voluntary contributions for gaps within the previous six tax years, but you should check whether filling the year will actually increase your pension first.
Can My Spouse’s National Insurance Record Help My State Pension?
The new State Pension is normally based on your own NI record, although limited inheritance and transitional rules involving a spouse or civil partner can apply.
Jennifer contributes business-focused articles covering modern business trends, digital growth, entrepreneurship, and practical insights designed to support startups and SMEs.
DWP Energy Bill Letters Dispatched: Six Million Households Could Get £150 Discount
Millions of UK households are being urged to watch their post as the Department for Work and Pensions (DWP) prepares to distribute letters concerning a £150 reduction in…
Kemi Badenoch Inheritance Tax Policy: What the 2026 Plan Could Mean
The Kemi Badenoch inheritance tax policy would make one of the biggest changes to the way family homes are treated for UK inheritance tax in decades if a…
Insights for the Modern
UK Small Business.
Join 15,000+ owners receiving tactical analysis on finance, marketing, and technology. No clutter.
Zero spam. Unsubscribe in one click.